
Categories
Homeownership, Hilton Head Island Real Estate, Buyer Resources, Coastal LivingHilton Head Island & Bluffton | Homeownership Guide
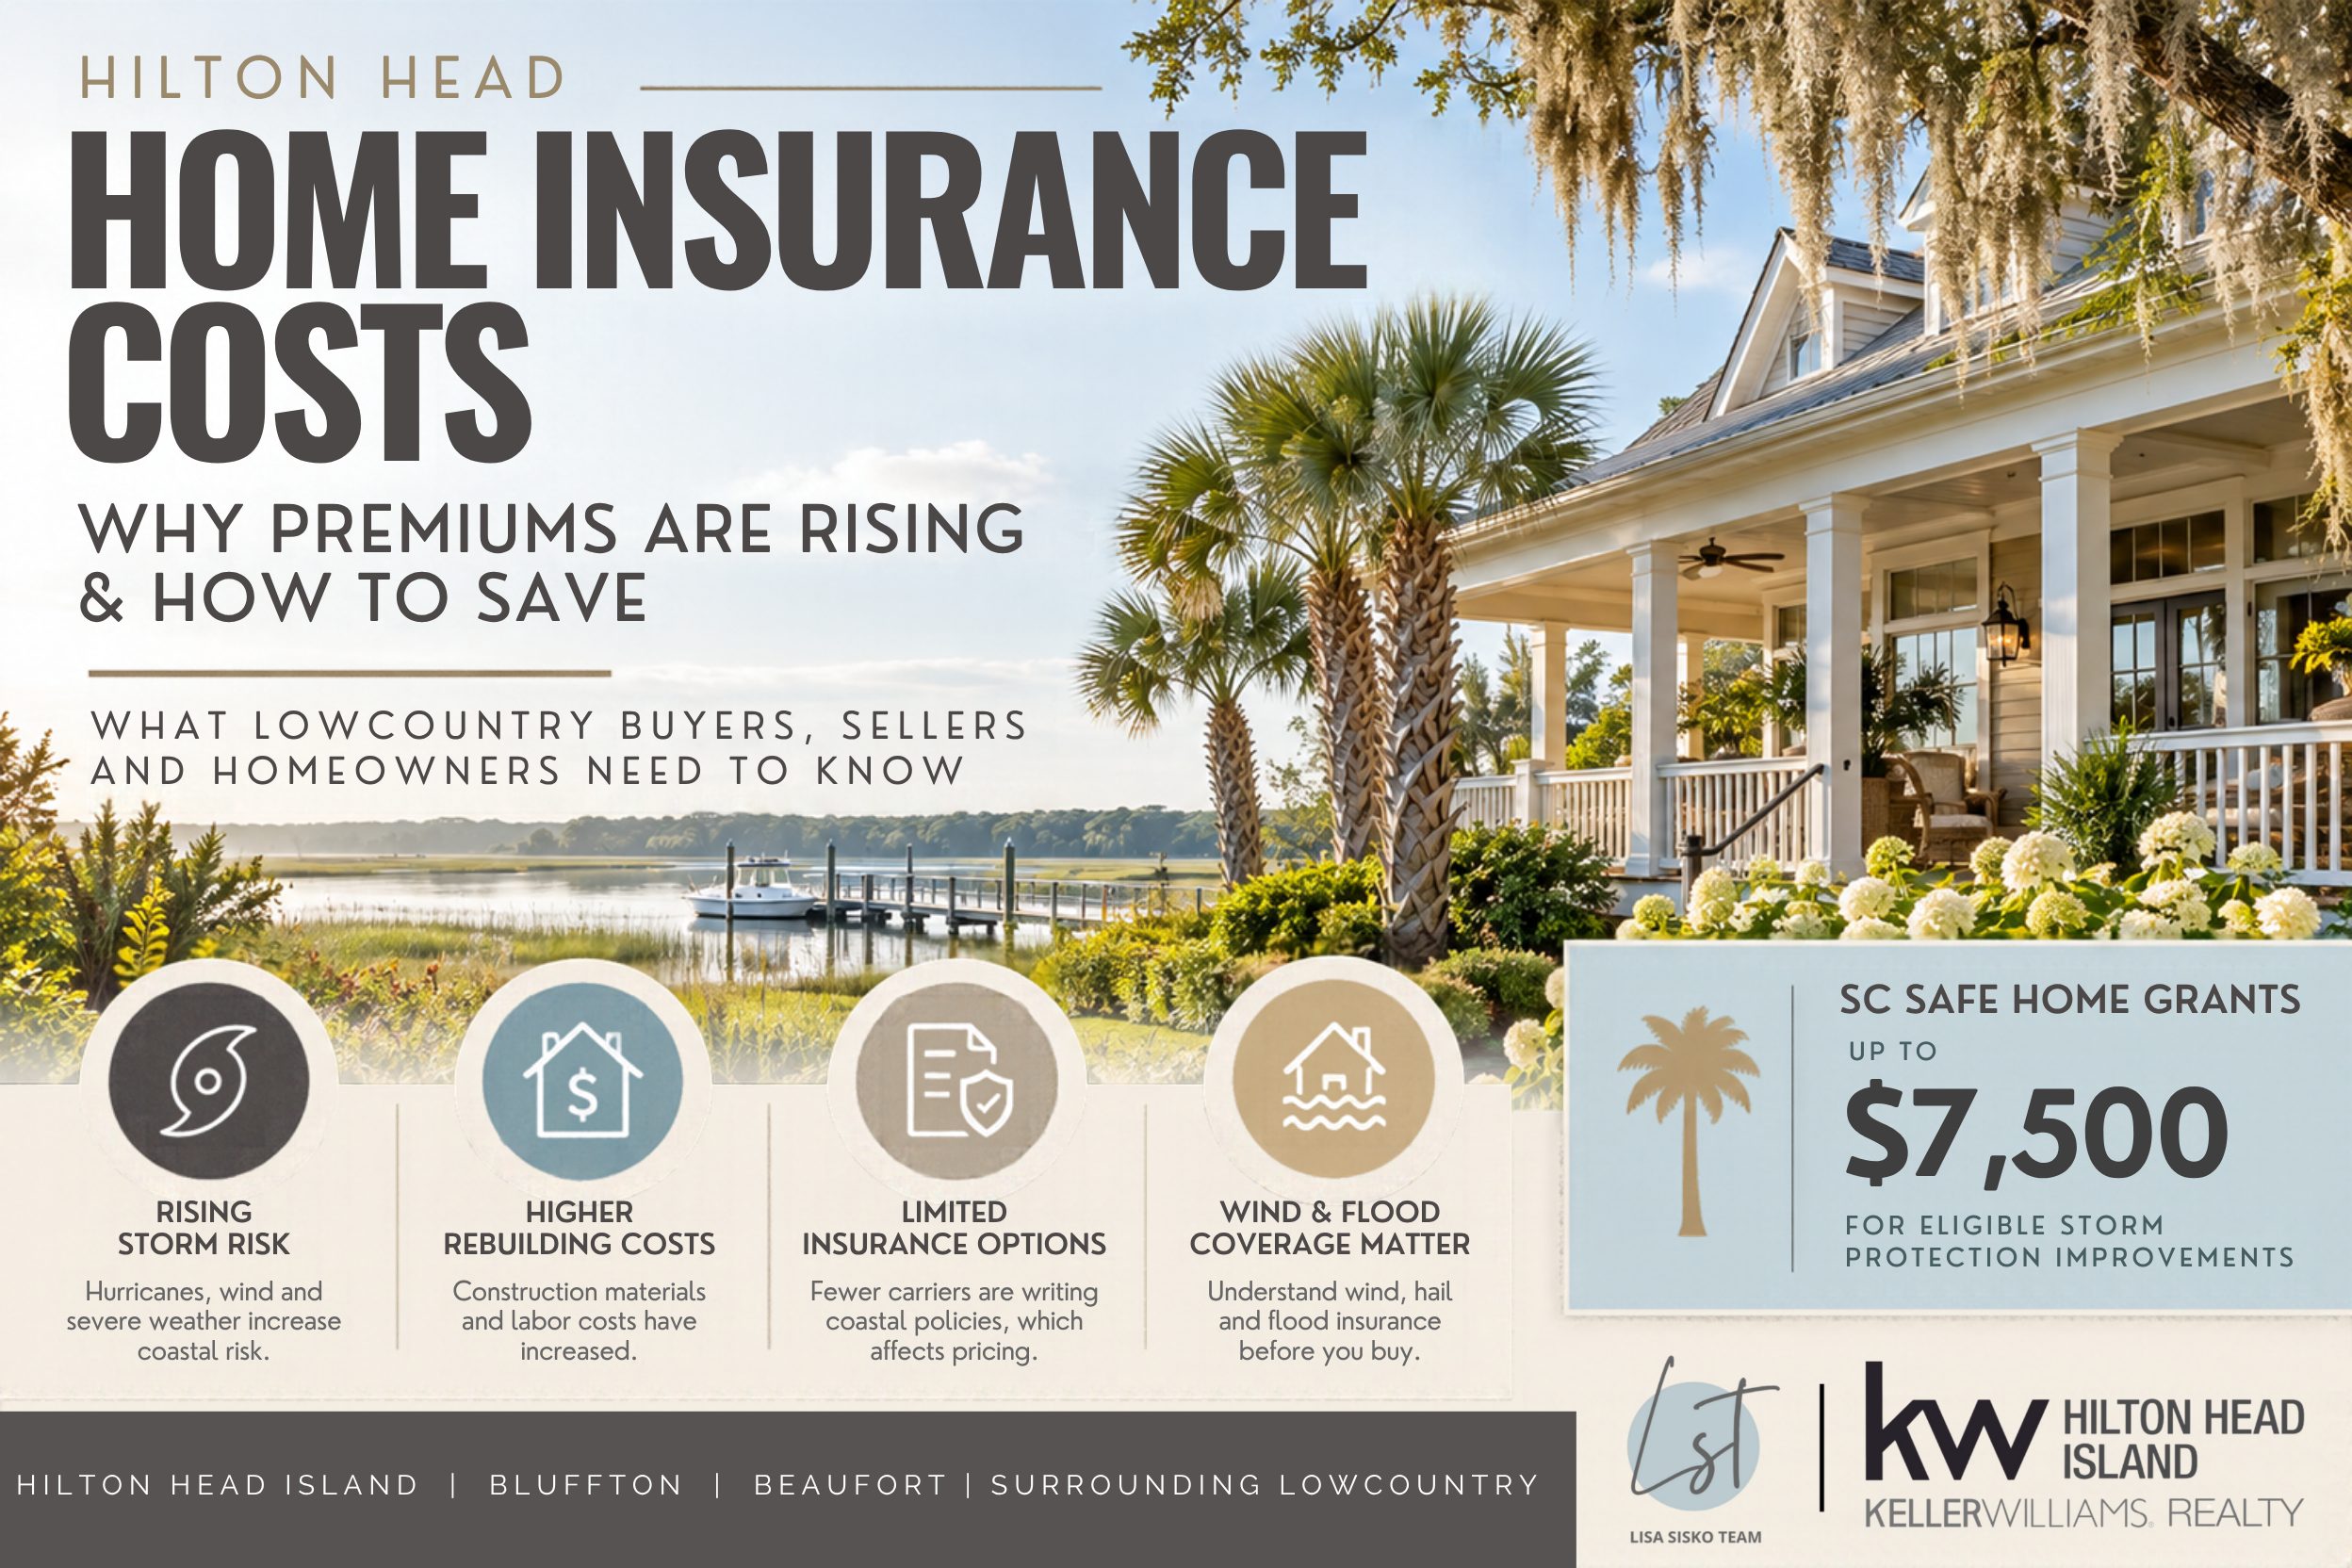
Hilton Head Home Insurance Costs:
Why Premiums Are Rising & How to Save
What Lowcountry buyers, sellers and homeowners need to know about coastal insurance, wind protection, flood coverage and potential savings.
You found the house. The kitchen is perfect, the neighborhood is beautiful, and the beach is just a bike ride away. Then the homeowners insurance quote arrives—and suddenly, the monthly cost of owning that dream home looks very different.
For buyers considering Hilton Head Island or Bluffton, South Carolina, homeowners insurance has become one of the most important expenses to investigate before purchasing.
Coastal properties face unique insurance challenges, but understanding your coverage and knowing where to look for savings can make a meaningful difference.
Why Is Hilton Head Homeowners Insurance So Expensive?
Several factors contribute to the cost of insuring homes along South Carolina's coast.
Hurricane & Wind Exposure
Coastal properties face greater risks from tropical storms, hurricanes and wind-driven damage.
Rising Rebuilding Costs
Construction materials, labor and replacement costs influence the expense of settling claims.
Insurance Market Pressures
Reinsurance expenses and restrictions on coastal coverage can limit available options.
Historical local reporting from 2023 described some homeowners experiencing premium increases of 20% to 70%, including one reported increase from $1,900 to $3,100 annually.
These figures are historical examples, not current average premiums. Actual costs depend on the property, carrier, coverage and deductible.
Wind & Hail Insurance: The Coverage Buyers Should Understand
One of the biggest surprises for Hilton Head homebuyers is discovering that wind and hail coverage may be handled differently from standard homeowners insurance.
Some policies include wind coverage, while others exclude it or apply a separate deductible.
For eligible coastal properties that cannot obtain wind and hail coverage through the standard market, the South Carolina Wind and Hail Underwriting Association (SCWHUA), commonly called the wind pool, provides an alternative.
The wind pool is a residual insurance market, not an automatic requirement for every coastal home.
Five Questions to Ask About Wind Coverage
- Does the homeowners policy include wind and hail?
- Will I need a separate wind policy?
- Is there a hurricane or named-storm deductible?
- Is the deductible a dollar amount or a percentage?
- What exclusions or coverage limitations apply?
Example: Understanding Your Deductible
$12,000
A 2% hurricane deductible on a home insured for $600,000 equals $12,000. Always understand the deductible before comparing premiums.
Flood Insurance Is a Separate Consideration
Standard homeowners insurance generally does not cover flooding. For Hilton Head and Bluffton properties, flood insurance may be a separate and significant expense.
Properties in FEMA-designated Special Flood Hazard Areas generally require flood insurance when financed with federally backed mortgages. Other lenders may impose additional requirements, and properties outside high-risk flood zones can still experience flooding.
When researching a property, request its flood zone information and ask whether an elevation certificate is available.
An elevation certificate documents certain elevation characteristics of a building and may help identify potential flood insurance savings. It does not guarantee a lower premium.
Can a Wind Mitigation Inspection Lower Your Insurance?
Potentially. A wind mitigation inspection evaluates and documents construction features that may help a home withstand severe weather.
Roof Construction
Roof shape, materials and attachment methods
Storm Protection
Qualifying shutters and protective barriers
Impact Protection
Impact-rated windows and doors
South Carolina recognizes insurance mitigation credits for certain qualifying improvements. However, savings vary by carrier, documentation and applicable requirements.
Before scheduling an inspection or making upgrades, ask your insurance agent which improvements qualify for discounts.
Financial Assistance for Coastal Homeowners
SC Safe Home Grants: Help Paying for Storm Protection
The South Carolina Safe Home Program, administered by the South Carolina Department of Insurance, provides grants to eligible coastal homeowners for qualifying hurricane and wind mitigation improvements.
$7,500
Up to
Qualifying resilient roof improvements
$5,000
Up to
Other eligible mitigation improvements
$3,000
Up to
Qualifying hurricane shutters and barriers
Maximum grant amounts and eligibility depend on program rules, income, matching requirements and the approved project. Awards are not guaranteed.
Important Program Update
Check SC Safe Home Program Availability → The SC Safe Home program was not accepting applications at the time of this article's preparation. Funding windows and application status can change. Visit the official website for current availability and notifications.
Is a FORTIFIED Roof Worth Considering?
The Insurance Institute for Business & Home Safety developed the FORTIFIED program to help strengthen homes against severe weather.
A qualifying FORTIFIED Roof may improve resistance to certain wind-related damage and may qualify for insurance benefits.
Not every roof replacement qualifies for a FORTIFIED designation. The project must meet the applicable construction and evaluation requirements.
If you're planning a roof replacement, talk with your insurance agent and a qualified contractor before beginning work.
Six Practical Ways to Lower Your Coastal Insurance Costs
01. Compare Multiple Carriers
An independent agent can compare available policies, coverage structures and deductibles.
02. Ask About Mitigation Credits
Existing storm-protection features may qualify for insurance savings.
03. Review Deductibles
A higher deductible may reduce premiums, but increases your potential out-of-pocket cost.
04. Document Roof Condition
Roof age, construction, condition and inspection records can affect underwriting.
05. Compare Bundled Policies
Bundling may save money, but compare against separate coverage options.
06. Re-Shop Before Renewal
Review pricing, exclusions and dwelling coverage annually.
For Hilton Head & Bluffton Buyers
Get Insurance Quotes Before Closing
Insurance should be part of your early due diligence, not something left until the week before closing.
When evaluating a property, ask about:
- Roof age, condition and replacement records
- Prior insurance claims and known damage
- Storm shutters, impact-rated windows and other protection
- Flood zone and available elevation documentation
- Existing wind mitigation or FORTIFIED certifications
Request property-specific quotes early enough to understand your options and meet financing or contractual deadlines.
Your True Monthly Ownership Budget
Mortgage + Property Taxes + Homeowners Insurance + Wind Coverage + Flood Insurance + HOA/POA Fees + Utilities + Maintenance
A home with a lower asking price may not have a lower total cost of ownership. If insurance expenses are unexpectedly high, review your contract and discuss your options with your real estate agent.
For Lowcountry Home Sellers
Insurance Documentation Can Help Buyers Feel More Prepared
Insurance is increasingly important to the purchasing decision. Sellers can help prospective buyers evaluate a property by gathering relevant records before listing.
- Roof replacement permits and warranties
- Wind mitigation inspection reports
- FORTIFIED Roof documentation, if applicable
- Storm shutter and impact-window specifications
- Available elevation certificates
These documents do not guarantee insurance savings, but they can help buyers and insurance professionals assess coverage options.
Frequently Asked Questions About Hilton Head Home Insurance
How much is homeowners insurance on Hilton Head Island?
There is no single premium that applies to every property. Costs depend on location, construction, insured value, roof condition, coverage, deductibles and carrier. Request current quotes for the specific home.
Does homeowners insurance cover hurricane damage in South Carolina?
Coverage varies. Wind damage may be included, excluded or subject to a separate deductible. Flooding from storm surge generally requires separate flood insurance.
What is the South Carolina wind pool?
The SCWHUA provides wind and hail insurance for eligible coastal properties that cannot obtain suitable coverage through the standard market.
Can hurricane shutters lower homeowners insurance?
Qualifying shutters and other protective features may earn mitigation credits. Requirements and savings vary by insurer.
Can Bluffton homeowners apply for SC Safe Home grants?
Eligible homeowners in qualifying coastal areas may participate when applications are open, subject to funding and program requirements.
Do I need flood insurance outside a high-risk flood zone?
It may not be required by your lender, but flooding can occur outside mapped high-risk areas. Review your property's risk and coverage options with an insurance professional.
Helpful Coastal Insurance Resources
Hilton Head Island & Bluffton Real Estate
Protect Your Investment Before You Buy
Buying a coastal home should be exciting, not full of unexpected expenses. The Lisa Sisko Real Estate Team can help you evaluate the total cost of ownership and connect with local insurance professionals.
Let's Talk About Your Hilton Head Home Search